2026 Conforming Loan Limits and Jumbo Loan Limits by County
Use the Colorado county tables below to confirm the applicable amount; a mortgage above that county limit is generally considered a jumbo loan.
Standard Loan Limits
$ 832,750
High-Cost Area Limit
$ 1,249,125
Special-area exception: Alaska, Hawaii, Guam, and the U.S. Virgin Islands have higher 2026 limits under federal law. For one-unit properties, the baseline limit is $ 1,249,125 and the ceiling is $ 1,873,675. FHFA publishes the applicable county-specific limits.
2026 Colorado Conforming and Jumbo Loan Limits by County
For a one-unit property, the limit that matters is the FHFA conforming loan limit for the county where the home is located. These are the 2026 limits for mortgages Fannie Mae and Freddie Mac may acquire. A conventional loan amount above the applicable county limit is generally a jumbo loan. This is a loan-amount test, not a home-price test.
These figures apply to one-unit properties. Two- through four-unit properties have different limits, and FHA, VA, and other loan programs use their own rules. Always confirm the property county and loan program before writing an offer or locking a loan.
Understand Your Loan Options
Colorado 2026 One-Unit Conforming Limits
Applies in most Colorado counties unless the property is located in one of the higher-limit counties below.
Higher-Limit Colorado Counties
Find the property county alphabetically and use the corresponding 2026 one-unit limit.
| County | 2026 limit |
|---|---|
| Adams | $862,500 |
| Arapahoe | $862,500 |
| Boulder | $879,750 |
| Broomfield | $862,500 |
| Clear Creek | $862,500 |
| Denver | $862,500 |
| Douglas | $862,500 |
| Eagle | $1,249,125 |
| Elbert | $862,500 |
| Garfield | $1,209,750 |
| County | 2026 limit |
|---|---|
| Gilpin | $862,500 |
| Grand | $883,200 |
| Jefferson | $862,500 |
| Lake | $1,092,500 |
| Moffat | $1,089,050 |
| Park | $862,500 |
| Pitkin | $1,209,750 |
| Routt | $1,089,050 |
| San Miguel | $994,750 |
| Summit | $1,092,500 |
View counties using the $832,750 standard limit
Alamosa, Archuleta, Baca, Bent, Chaffee, Cheyenne, Conejos, Costilla, Crowley, Custer, Delta, Dolores, El Paso, Fremont, Gunnison, Hinsdale, Huerfano, Jackson, Kiowa, Kit Carson, La Plata, Larimer, Las Animas, Lincoln, Logan, Mesa, Mineral, Montezuma, Montrose, Morgan, Otero, Ouray, Phillips, Prowers, Pueblo, Rio Blanco, Rio Grande, Saguache, San Juan, Sedgwick, Teller, Washington, Weld, and Yuma counties.
Conforming vs. Jumbo: What Changes?
Conforming: A conventional loan at or below the applicable county limit may be eligible for purchase by Fannie Mae or Freddie Mac, provided it also meets the lender’s and the Enterprise’s underwriting requirements.
Jumbo: A loan above that county limit is outside the conforming limit. Lenders set their own jumbo guidelines for credit, income, assets, reserves, down payment, property type, and documentation.
Pricing and cash to close: Neither the interest rate nor the required down payment is determined by the word “jumbo” alone. Compare the full offer—rate, points, fees, reserves, and cash to close—based on the borrower and the property.
Colorado Borrower Examples
- Denver: A buyer seeking a $ 850,000 loan on a one-unit home is below Denver County’s $ 862,500 limit, so the loan could be conforming if it meets all other conventional requirements. At $ 900,000, it would generally be jumbo.
- Eagle County: A $ 1,150,000 one-unit loan is below Eagle County’s $ 1,249,125 limit and could be conforming; a $ 1,300,000 loan would generally be jumbo.
- Pitkin County: A $ 1,200,000 one-unit loan is below the $ 1,209,750 limit. A $ 1,220,000 loan is above it and would generally be jumbo.
Estimate Your Jumbo Mortgage Payment
Jumbo Calculator
Estimate the monthly payment on a jumbo loan, used for purchase prices above the conforming loan limit. Defaults are tuned for typical high-balance scenarios.
Calculator inputs
Estimated payment
The Mortgage Architects is a registered DBA of Independent Mortgage Brokers, LLC, NMLS #2191655. Calculator results are estimates provided for informational and illustrative purposes only and do not constitute a loan application, loan approval, commitment to lend, or guarantee of rates or terms. Any interest rate shown is not an APR and may exclude fees and other costs. Actual eligibility, rates, APR, payments, and costs may vary based on creditworthiness, property details, loan program requirements, market conditions, and final underwriting approval. Loan products and services are available only in states where properly licensed. Equal Housing Lender. For licensing information, visit www.nmlsconsumeraccess.org.
NMLS# 2191655
Get your personalized report
-
Year-by-year amortization schedule showing principal paid, interest paid, and remaining balance Year Principal Interest Balance
Report Sent!
Check your inbox. Your personalized mortgage report is on its way. A PDF copy has also been downloaded to your device.
Why the Limits Change Each Year
Under the Housing and Economic Recovery Act, FHFA adjusts the national baseline conforming limit annually using the change in average U.S. home prices. The 2026 baseline is $832,750—$26,250 higher than 2025. In high-cost areas, the county limit can be higher, up to the 2026 ceiling of $1,249,125 for one-unit properties.
Source: Federal Housing Finance Agency 2026 Conforming Loan Limit Values and county list. A mortgage professional can confirm the county limit, program requirements, and loan structure for a specific purchase or refinance.
Not Sure Which Colorado Loan Limit Applies?
Share the property county and estimated loan amount. The Mortgage Architects can confirm whether the scenario may be conforming or jumbo and explain the available options— no obligation.
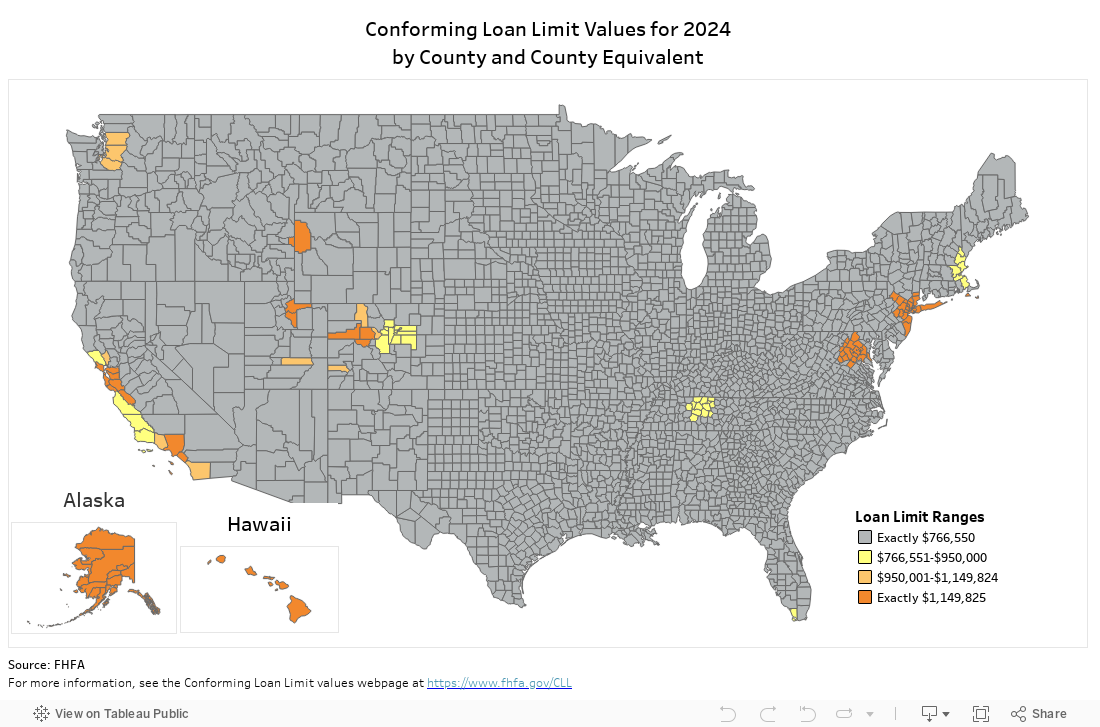
Explore the Interactive County Loan-Limit Map
What Is a Jumbo Loan?
Jumbo loans finance higher-priced homes that fall outside the conforming limits used by Fannie Mae and Freddie Mac. They often receive closer review of income, assets, credit, reserves, and the property itself.
The right structure can vary significantly from one lender to another, especially for self-employed borrowers, buyers with complex assets, and people who want to preserve cash rather than place more money into the transaction.
Why the Lender Choice Matters More on a Jumbo Loan
In the short video below, Nathan explains why a familiar bank name does not necessarily produce the strongest jumbo-loan offer or the smoothest closing. The larger the loan, the more even a small difference in rate, fees, or structure can affect both monthly cost and long-term capital.
Jumbo Loan Broker vs. Big Bank
A large bank can generally offer only its own jumbo products and its own underwriting rules. An independent mortgage broker can compare several lenders and match the loan structure to the borrower, property, timeline, and overall financial plan.
| What to Compare | Banks | The Mortgage Architects |
|---|---|---|
Lender access | The bank’s own portfolio and programs | More than 70+ wholesale lenders |
Guidelines | One institution’s credit and underwriting approach | Multiple programs that may fit different income, asset, reserve, and property profiles |
Pricing | The bank’s available rate and fee structure | Wholesale options compared for rate, fees, cash-to-close, and long-term cost |
Preapproval | Process and response times vary by institution | Early review and pre-underwriting when appropriate before an offer is made |
Closing management | Often divided among departments | The Mortgage Architects manage communication and milestones through closing |
Loan programs, approval, pricing, and terms vary by lender and borrower qualifications. Comparing lenders does not guarantee approval or a particular rate.
How The Mortgage Architects Approaches a Jumbo Loan
Consulta gratuita
We review the purchase goals, income, assets, reserves, property type, and preferred cash strategy.
Preapproval
The file can be reviewed or pre-underwritten before the buyer goes under contract when appropriate, giving the borrower and listing agent more confidence in the financing.
Compare Lenders
Once the property and transaction details are clear, the team compares suitable wholesale lenders and weighs rate, fees, reserves, down payment, and flexibility.
Closing
The Mortgage Architects coordinates underwriting, appraisal, conditions, communication, and the closing timeline from contract to completion.
Who May Benefit from Comparing Jumbo Lenders?
- Buyers purchasing above the conforming loan limit in their county
- Self-employed borrowers or people with complex income
- Borrowers with substantial assets who want to preserve liquidity
- Buyers considering different down-payment or reserve strategies
- Anyone who wants a lender and preapproval that can support a competitive offer


Frequently Asked Questions About Jumbo Loans
A jumbo loan is a mortgage amount above the conforming limit for the Colorado county where the property is located. Because some counties receive higher limits, the same loan amount may be conforming in one county and jumbo in another.
No. The required down payment depends on the lender, loan amount, property, credit profile, reserves, and other qualifications. Nathan can compare available programs and show how different down-payment choices affect the complete loan.
Not necessarily. Jumbo pricing changes with lender appetite, market conditions, borrower strength, and loan structure. That is why comparing more than one lender can be especially valuable for a larger balance.
Listing agents evaluate whether financing is likely to close on time. A thorough preapproval, responsive communication, and a lender or broker with a dependable process can make an offer easier to evaluate—particularly on a higher-priced property.
It depends on the borrower and the transaction. A bank may be competitive for a client who fits its portfolio, while a broker can compare multiple lenders instead of relying on one institution’s program. The goal is to choose the best overall fit, not simply the most familiar brand.
Not Sure Whether Your Loan is Conforming or Jumbo?
Let’s find out together. Get expert guidance and a clear next step.
- Quick review of your property & loan scenerio
- Fast, no-obligation feedback
- Local expertise you can trust